

by Doug Brodie
The Americans go one step further with their warning signs:
Life will kill us all, it’s a fatal condition, however in the meantime, we’d better do some living!
[1] Year-by-Year (Mike & the) Mechanics: The Investment Trust "Shortfall Bridge" (Ages 65-75)
When you hold £100,000 in a basket of Dividend Hero investment trusts yielding 4.5% with 4.0% annual capital and dividend growth, your total annual return is 8.5% (4.5% natural yield + 4.0% capital growth).
If you need £8,260/year to match the age-65 annuity, you take the natural dividend first and sell a tiny sliver of shares (capital) at the end of each year to cover the shortfall:
Year 1 (Age 65-66): The £100,000 portfolio generates £4,500 in dividends, and the underlying capital grows by 4.0% (+£4,000) to £104,000. You draw the £4,500 dividend plus £3,760 from capital to get your £8,260 income. Your closing pot at the end of Year 1 actually rises to £100,240 (£100,000 + £4,000 capital growth - £3,760 capital drawdown).
Every Year Thereafter: Because your total return (8.5%) slightly exceeds your initial 8.26% withdrawal rate, your capital base never erodes below £100,000! Instead, both the capital value and the 4.5% dividend yield compound slowly upward:
By Year 5 (Age 70), the pot is worth £101,383, paying £4,562 in natural dividends and requiring £3,698 from capital.
By Year 10 (Age 75), the pot has grown to £103,404, paying £4,653 in natural dividends and requiring just £3,607 from capital.
Note: Even under a more conservative variant where total return is lower - say 2.0% capital price growth + 4.5% yield = 6.5% total return - the pot at age 75 still retains £80,692, buying £8,214/yr at the 10.18% annuity rate. Now life is not as organised as that, and what happens is that the market will fall when you need to sell capital and then it kind of all gets a little messy. That’s why the structured discipline and experience we have helps to make sure it works, every year, for every client.
[2] "Stayin' Alive" - Inheritance, Legacy & Longevity
Passing wealth smoothly down generations, tax-efficient drawdown order, and long-term vitality.
1970s Cultural Anchor: The Bee Gees’ Stayin' Alive (Saturday Night Fever, 1977) came out in the same year as The Muppet Show album hit #1, and Never Mind the Bollocks hit #2. The Clash, The Jam and, of course, we can’t forget The Stranglers’ Rattus Norvegicus. How many of these 1977 hits did you have?
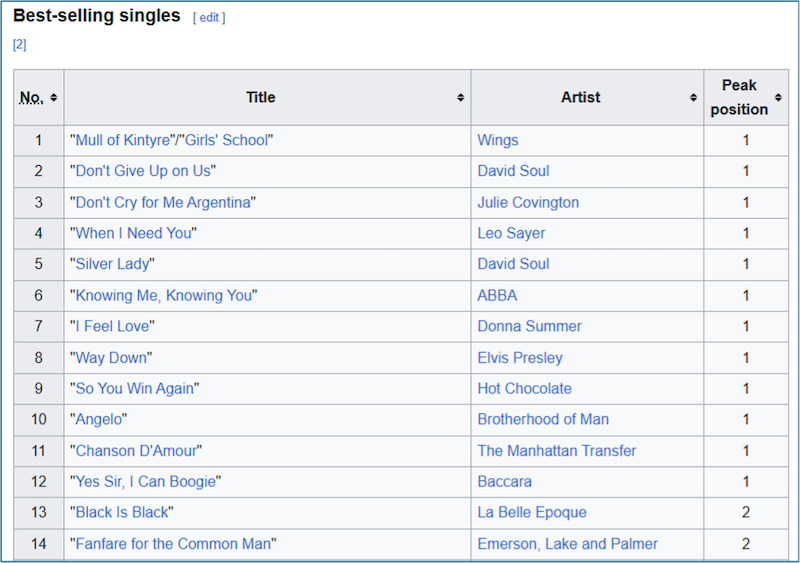
It doesn’t last for the Bee Gees though: Sir Barry has just turned 80, but Maurice died at 53, Robin at 62 and Andy at just 30. They say we are just caretaking wealth for the next generation, and with pensions due to fall into the IHT rabbit hole, we should take a look.
The 4 Detailed Core Ideas
1. The Inheritance Tax (IHT) Decumulation Waterfall
Pension Strategy: Understand the hierarchy of which assets to spend first.
Analysis: With pensions traditionally sitting outside the estate for IHT (and subject to ongoing legislative reviews regarding inheritance rules), follow the "Waterfall Rule": spend taxable cash and unwrapped portfolios first, tap ISAs strategically, and preserve SIPPs for heirs where appropriate to maximise multi-generational wealth.
2. Bed & ISA and Capital Gains Harvesting
Financial Methodology: Working within the frozen nil-rate bands and reduced £3,000 Capital Gains Tax allowance per investor.
Analysis: Systematically migrate non-registered shares and general investment accounts (GIAs) into Stocks & Shares ISAs up to the £20,000 annual limit (or £40,000 across a married couple/civil partnership), creating an entirely tax-free future income stream.
3. The Punk Ethos of Longevity: Refusing to "Go Quietly"
70s Culture & Mindset: 1977 wasn't just disco, it was the raw, anti-establishment energy of punk.
Analysis: Reject the passive model of ageing. We address the biological necessity of resistance training, grip strength, and cognitive friction (learning complex new skills) to protect the healthspan that makes pension independence enjoyable in the first place.
[3] The Family Wealth Transfer Checklist: Why a Will Isn’t Enough
The 5-Point Estate & Digital Legacy Audit Every Family Needs
1. Ask most people if their affairs are in order, and they'll proudly tell you they have a Will. While a Will is a vital starting point, in today's world of complex pension legislation, discretionary investment portfolios, and Two-Factor Authentication, relying solely on a Will is a bit like locking your front door while leaving the back patio wide open.
2. When a family experiences a sudden medical emergency or bereavement, the emotional toll is heavy enough. Yet time and again, loved ones find themselves locked out of online accounts, facing frozen bank balances, or losing thousands of pounds in avoidable Inheritance Tax (IHT) simply because small administrative details were overlooked while everyone was healthy.
3. To protect your wealth and spare your family months of legal and administrative stress, your estate plan needs to go beyond a dusty document in a solicitor's safe. Here are the five essential pillars of a modern Estate and Digital Legacy Audit.
1. Lasting Powers of Attorney (LPAs) & Mental Capacity
4. Many people assume a spouse or business partner can automatically step in to manage their finances if they lose mental capacity, or that simply signing an LPA form is enough to stay protected.
5. In reality, without a valid LPA in place, even joint bank accounts can be frozen by the bank if one partner loses capacity, leaving the other unable to access family funds without a costly, six-to-twelve-month application to the Court of Protection. Furthermore, an LPA cannot be used until it is formally registered with the Office of the Public Guardian (OPG) - a process that currently takes 8 to 16 weeks.
6. A proper audit checks three critical details:
Registration & Access: Are both your Property & Financial Affairs and Health & Welfare LPAs registered with the OPG, and do you have your digital OPG access codes ready?
How Your Attorneys Act: Are your attorneys appointed 'jointly and severally'? If they are appointed strictly 'jointly' and one attorney dies or loses capacity, the entire LPA fails.
Investment & Business Continuity: Does your financial LPA include specific wording permitting your attorneys to continue using a Discretionary Fund Manager (DFM), and - if you run a company - do you have a separate Business LPA aligned with your Articles of Association?
2. Wills, Trusts & Estate Structure
7. A Will remains the cornerstone of your estate plan, yet major life events - such as marriage, divorce, welcoming grandchildren, or changes in tax rules - can quietly render an older Will obsolete. Did you know, for instance, that marriage in England and Wales automatically revokes an existing Will unless it was explicitly written in contemplation of that marriage?
8. Reviewing your estate structure means checking when your Will was last updated, ensuring the physical original hasn't been tampered with (even attaching a paperclip or staple to an original Will can trigger probate queries over missing pages!), and confirming your chosen executors are still willing and able to act. It's also the ideal time to add a Digital Executor clause and verify that any existing family trusts are fully registered and up to date on HMRC's mandatory Trust Registration Service (TRS).
3. Pension Expressions of Wish & Policy Nominations
9. One of the biggest misconceptions in financial planning is that your pension passes through your Will. It doesn't. Pensions and life insurance policies are typically governed by scheme trustees, who rely on your Expression of Wish to decide who receives the funds.
10. Getting your Expression of Wish wording right matters for two major reasons:
Preserving Tax-Efficient Drawdown for Your Children: Under UK pension rules, if you pass away leaving a surviving spouse, your adult children can only inherit a share of your pension via Nominee's Flexi-Access Drawdown (allowing the funds to remain invested rather than paying out as a taxable cash lump sum) if those children were explicitly named on your Expression of Wish during your lifetime - even if only at 1%.
Preparing for the April 2027 Pension IHT Changes: With unused pension funds scheduled to be brought into the UK Inheritance Tax net from April 2027, reviewing who inherits your pension versus your ISA and non-pension assets - and ensuring your life insurance policies are written in trust so payouts don't swell your taxable estate - has never been more urgent.
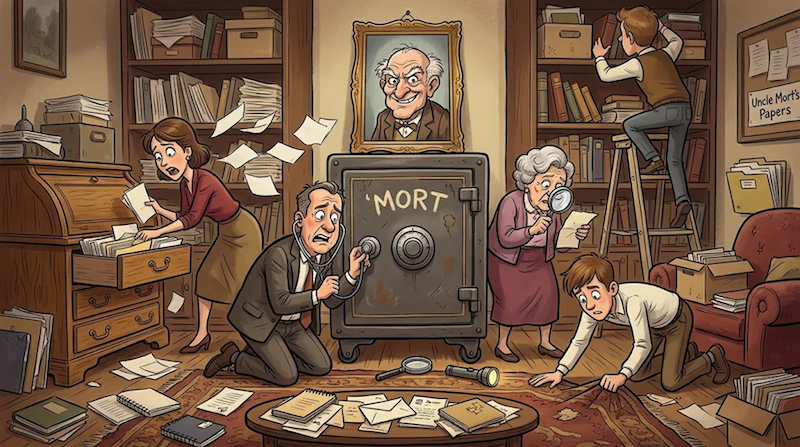
4. Digital Assets, Passwords & the '2FA Lockout' Problem
11. We now live in a paperless world. Bank statements arrive by email, investments are held on digital platforms, and nearly every account is protected by Two-Factor Authentication (2FA) sent to a smartphone.
12. This creates a modern probate nightmare: biometric locks like Face ID and Touch ID cease to work upon death or incapacity. Without your phone's PIN and a lawful way to access your credentials, your executors can be completely locked out of your digital life - from online-only bank accounts and utility bills to cryptocurrency wallets, airline Avios balances, and decades of treasured family photos in the cloud.
13. Because a Will becomes a public document once Probate is granted, you must never write passwords, PINs, or crypto seed phrases inside your Will. Instead, a robust digital legacy plan involves:
Password Manager Emergency Kit: Storing your credentials in a reputable Password Manager and printing out its 'Emergency Kit' (along with your smartphone unlock PIN) to keep in a sealed envelope in your home safe or with your solicitor.
Built-In Platform Legacy Tools: Taking five minutes on your phone today to set up an Apple Legacy Contact (for iPhone/iCloud) and Google's Inactive Account Manager (for Gmail/Google Photos) so your chosen loved ones are granted seamless, legal access when the time comes.
5. The 'In Case of Emergency' (ICE) Directory & Lifetime Gifting Log
14. When a crisis hits, the last thing your family needs is a treasure hunt through drawers and filing cabinets to work out which banks you use, where the house deeds are, or who advises you.
15. Creating a single 'In Case of Emergency' (ICE) Directory brings everything together in one place: the contact details of your financial planner, solicitor, and accountant, alongside the exact location of marriage and birth certificates, share certificates, and funeral wishes.
16. Crucially, your ICE folder should also contain an up-to-date-7-year Lifetime Gifts Log (aligned with HMRC Form IHT403). If you regularly help children with school fees, mortgage deposits, or gifts out of your surplus income, recording those gifts year by year gives your executors the exact evidence they need to claim immediate Inheritance Tax exemptions -such as the highly valuable 'Normal Expenditure out of Income' exemption - potentially saving your family tens of thousands of pounds in unnecessary tax.
Take the next step: put your family’s mind at ease
Sorting out your LPAs, Expressions of Wish, and Digital Legacy doesn't take weeks of legal legwork - it just takes a structured checklist and a single focused conversation.
To help you get started, we have put together a Comprehensive Estate, LPA & Digital Legacy Audit Checklist that we work through with our clients to ensure nothing falls through the cracks.
Would you like a copy of our Audit Template, or a second pair of eyes on your current arrangements? Get in touch with our team today on 020 7390 0670 or email hello@chancerylane.net to request your free copy of the Audit Checklist or to book a no-obligation review of your pensions, estate plan, and family protection.
🧠 Grey Matter Workout: the answer
“One morning a little rabbit sat on a bank.” - The Tale of Benjamin Bunny by Beatrix Potter (1904)
"When Mary Lennox was sent to Misselthwaite Manor to live with her uncle everybody said she was the most disagreeable-looking child ever seen." - The Secret Garden by Frances Hodgson Burnett (1911)
“I hadn't spoken to him. Then he tries to poison that nice little thing next door with some vile stuff I thought I'd thrown away...” - Just William by Richmal Crompton (1922)
"Mother, have you heard about our summer holidays yet?” - Five on a Treasure Island by Enid Blyton (1942)
“Once there were four children whose names were Peter, Susan, Edmund and Lucy.” - The Lion, the Witch and the Wardrobe by C. S. Lewis (1950)
"If, standing alone on the back doorstep, Tom allowed himself to weep tears, they were tears of anger." - Tom's Midnight Garden by Philippa Pearce (1958)
"It was Mrs. May who first told me about them." - The Borrowers by Mary Norton (1952)
“Where’s Papa going with that axe?” - Charlotte's Web by E. B. White (1952)
About the author
Doug Brodie is Founder and CEO of Chancery Lane Income Planners. He has specialised in retirement income for over thirty years and is Chartered with both the CISI and CII. This article is general information and not personal advice. Tax rules can change, and the impact of any planning depends on your specific circumstances. Capital is at risk and past performance is not a guide to future returns.