by Doug Brodie
[1] I’m 48 and I’ve hardly got a pension. Have I left it too late?
There are two times to get to grips with your pension savings: the ideal time, and now. And if you missed the ideal time, it’ll have to be now.
First things first: if you’ve been working for the best part of 30 years, you may have more pension savings than you think.
Workplace pensions have changed enormously during your working life. Stakeholder pensions arrived in 2001 and automatic enrolment started rolling out in 2012. So before deciding you have “hardly anything”, find out what you’ve actually got.
1. Start with your old jobs.
Make a list of the places you’ve worked and any pensions you remember having. This may involve getting that box down from the loft and going through old paperwork. We highly recommend it.
2. Check your State Pension.
You can check your State Pension forecast on the gov.uk website. This will give you an idea of how much you may receive, when you can receive it, and whether you may be able to increase it.
3. Look at today.
If you’re employed, make sure you’re in your current workplace pension. Your employer will pay in too, and some employers will pay more if you pay more. It’s essentially free money.
4. Do what you can now.
You’re not going to magically create a £1 million pension pot in the next year or so. But you can find out what you already have, understand where you’re starting from and begin adding to it. And at 48, there are still many working years ahead of you.
So have you left it later than ideal? Maybe.
Have you left it too late to do anything about it? Absolutely not.
[2] What actually is an ISA?
ISA stands for Individual Savings Account. ISAs were introduced on 6 April 1999, replacing two earlier tax-efficient schemes called PEPs and TESSAs.
An ISA isn’t an investment itself. It’s a tax-free wrapper that you can put savings or investments inside.
Cash ISA – you save cash and the interest you earn is free from UK Income Tax.
Stocks & Shares ISA – you can hold investments, and you don’t pay UK Income Tax on the income or Capital Gains Tax on gains within the ISA.
For the 2026/27 tax year, you can put up to £20,000 into ISAs. You don’t need anywhere near £20,000 to have one – that’s simply the maximum annual allowance.
[3] Average house prices then and now
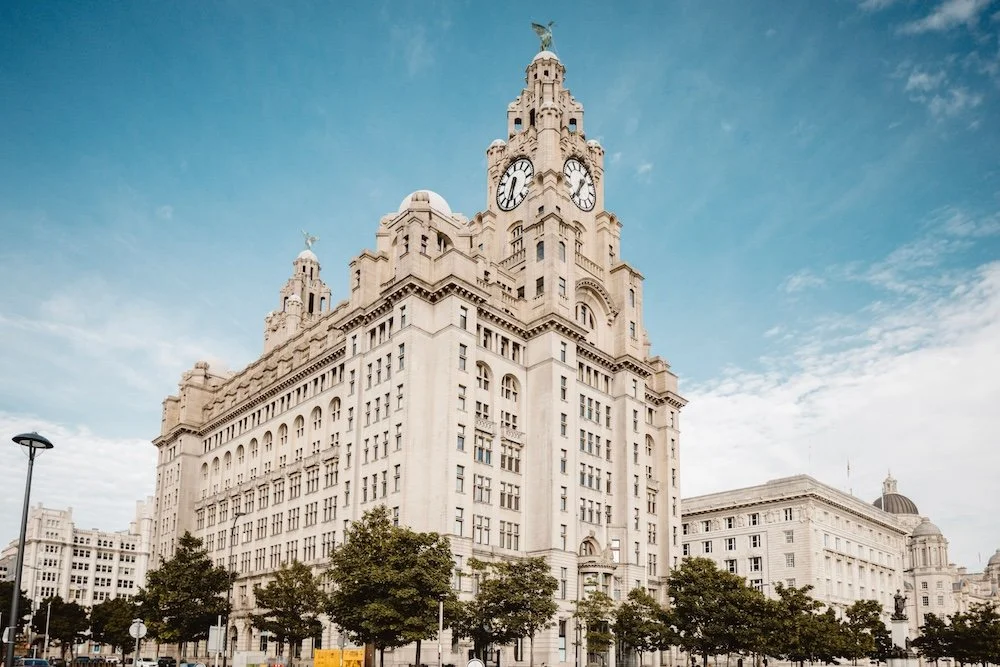
House prices have changed dramatically since 2000. Here’s how the average price in London and Liverpool compares with today.
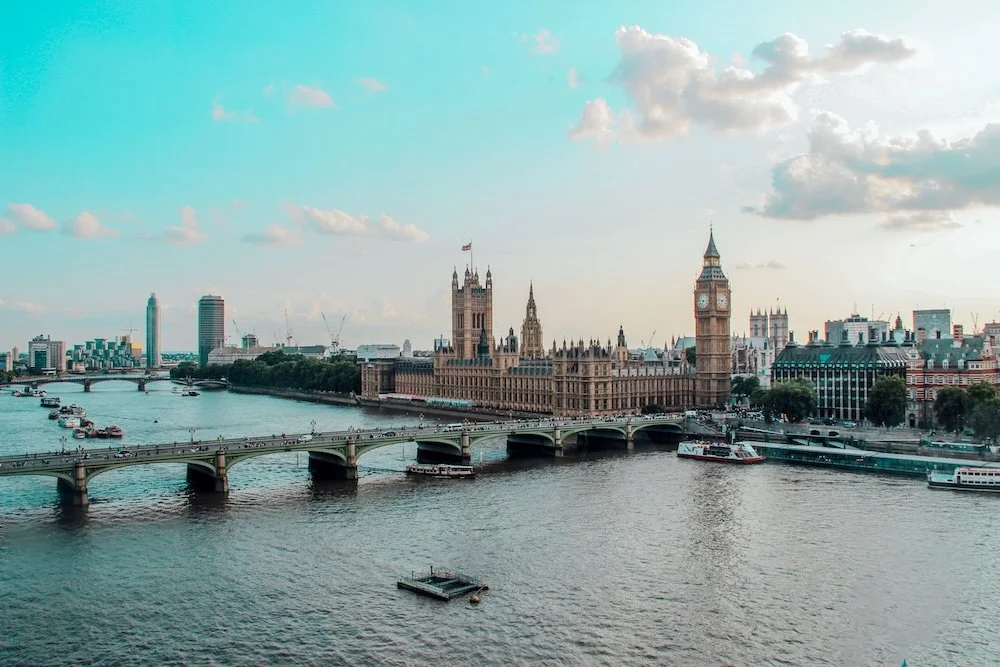
London
2000: £95,000
2024: £525,000
+453% increase
Liverpool
2000: £49,000
2024: £156,000
+218% increase
That’s more than a fourfold increase in London, and just over a threefold increase in Liverpool, since 2000.
Source: Land Registry UK House Price Index (average property price, 2000 and 2024, for London and Liverpool).
[4] True or false?
“My employer says we’re too small to have a workplace pension.”
FALSE
It doesn’t matter whether you work for a huge company or a tiny business. Employers have workplace pension duties from the day their first member of staff starts work.
If you’re aged 22 to State Pension age, usually work in the UK and earn at least £10,000 a year, your employer will normally have to automatically enrol you into a workplace pension and contribute to it.
[5] Food for tought

It’s not about being perfect. It’s about making progress for Future You.